Weyay Bank · Sr. Product Designer · 2021 – 2023
Loans
Helping young Kuwaitis get a loan from their phone and stay in control of it.


Loan amount
KWD45,0001,00060,000
Loan period
10years
115

Insure your loan?
1.1 KWD/Month

Delay first installment?
Monthly installment
Number of installments
120
% of your salary22%
Total amount
KWD51,653.957Housing loan

Context
Weyay launched with digital onboarding, account management and the allowance transfer. Lending was the second phase: a product a customer has to qualify for, and one that keeps people at the bank working long after the customer taps a button.
The bank’s proposition for it fit in one sentence.
Provide a quick, smooth and fully digital loan to achieve their goals and dreams with the flexibility and tools to feel in control of their debt.
Its own research had already named what people disliked about loans: a tedious process, no transparency, jargon, and no way to feel in control of the debt once they had it. Until then a loan meant a branch. A relationship officer checked the documents, asked for the missing ones, and the contract was signed on paper.
The product is also one of the most regulated a bank has. A consumer loan goes up to KWD 25,000 over at most five years, a housing loan up to KWD 70,000 over fifteen. All of a customer’s installments together cannot pass 40% of their salary. What they already owe elsewhere is read from the national credit bureau, and only with their consent. And once a loan is approved, the Central Bank gives the customer two days to change their mind before the money moves.
TODO (Guillem): what the bank wanted this to move, in its own numbers: applications, time to approval, share of loans started in the app.
My role
TODO (Guillem): what you owned in Loans and what Luca Artorelli owned, who else was on the team (R/GA, the bank’s product owner, the digital lending team), how long it took and how far it got: concept, tested prototype or shipped.
Process
Finding where to be different
Before any screen, we looked for the place where a loan from Weyay could be different from every other loan in Kuwait. It took four steps, each feeding the next.
How we found our differentiation and the features to recommend
- Audience and opportunity mapping
- Jobs to be done mapped across the journey, a competitor analysis, and the opportunities at each stage of the journey.
- Themes and concepting
- Jobs to be done grouped into themes by unmet need, a hypothesis for each key feature, concepts across the journey, and a shortlist to test.
- User testing
- Qualitative sessions and card sorting, then a synthesis of the results.
- Feature prioritization
- The desirability of the key features validated, the backlog put in order, and the sprints planned.
Three findings came out of the first step, and they set the direction for everything after.
Finding differentiation
- Loan data analysis
- About 52% of loans are taken out by customers aged 20 to 35. About 45% are for KWD 1,000 to 11,000, and 15% for KWD 16,000 to 26,000.
- Competitor analysis
- Every loan on the market required paper forms, documents and a physical signature.
- Loan proposition
- Digital first. Convenient and driven by a goal. Flexibility and control.
So the people who borrow most are the people the bank was built for, most of what they borrow is modest, and nobody was letting them do it without paper.
Four things a customer asks for
The bank described the product as six modules, the way it is organized: application, verification, underwriting, final contract, tracking, overview. A customer does not see modules. The jobs to be done gave the design its own structure, four requests in the customer’s voice: help me discover, help me apply, help me track, help me manage.
TODO (Guillem): confirm the four themes as the team named them, and which features testing ranked highest. Also check the map: that a saved application is picked up again from the card on Home is my reading of "Save your progress", not something the screens show.
Before you apply
On Home, a card under the account balance introduces loans. Opening it does not start a form. It starts with what applying takes, so nobody reaches the fifth screen to learn they cannot go on: being over 21, having a salary paid into Weyay, having no debt in arrears.
Then comes the step no branch application has. The app asks for consent, confirms it with a one-time code, and reads the customer’s commitments from the credit bureau: cards, loans, with this bank and with others. They see their own list before the bank says anything about it.
Aim higher
Life can’t wait. Get a loan that’s right for you and unlock tomorrow, today.
Loans for your lifestyle

It’s all digital
No need to visit a branch. Apply and get your funds from the comfort of your phone.

Prepay your loan
At any point you can clear part or all of your remaining balance.
Personal loans
0% Personal loan
Up to KWD15,000
up to 5 years
 Tell me more
Personal loan
Up to KWD15,000
up to 5 years
 Tell me more
Housing loans
Housing loan
Up to KWD70,000
up to 15 years
Tell me more
Interest rate at 2.75%. Why this rate?
Loans
TODO (Guillem): the rest of this part: the entry card on Home, "Before you apply", the one-time code and the list of commitments.
Offers, not a blank form
With the salary and the commitments known, the bank already knows the most it can lend and the highest installment it is allowed to charge. So the app does not ask how much the customer wants. It shows what they can get: one offer for each kind of loan, each with its maximum amount, its rate and its longest term.
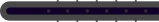
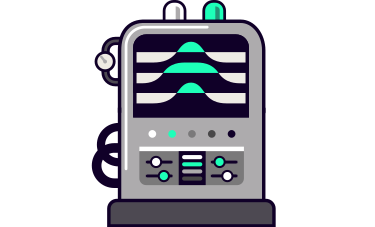
Working that out takes a few seconds, and the wait got a screen of its own: a machine. Cards ride in on a belt, gray, and come out the other side in mint, one for each loan being made.
Creating your loans...
TODO (Guillem): why offers came before the calculator: was a calculator-first version explored or tested?
The calculator
One screen holds every choice that changes the price: the amount, the term, insurance, and delaying the first installment by up to three months. Each of them moves the monthly installment and the total as it is touched, so the cost of a choice shows before it is made.
The two sliders are drawn after the logo: a gray stripe with a mint bump that steps out of it, dragged with a finger. One rises from the track and the other hangs under it, as the stripes of the mark alternate.
The limits are not the bank’s to set: installments cannot pass 40% of a salary. The calculator shows that as it happens. Under the installment, a line marks its share of the salary; at the limit the figure turns to the alert color. Push the amount past it and the amount’s own handle turns too, the period is set aside until the amount comes back down, and Continue goes gray. Nothing is refused with a message: the screen simply stops agreeing.
One tap from it, a screen says whose the limits are and what each one is, in the same voice as the rest of the app: what the central bank allows, what the insurance is for (“covered even if you...you know...die”), and what delaying the first installment really costs, which is fewer and higher installments.
Loan amount
KWD45,0001,00060,000
Loan period
10years
115
Insure your loan?
1.1 KWD/Month
Delay first installment?
Monthly installment
Number of installments
120
% of your salary22%
Total amount
KWD51,653.957Housing loan
Documents and one last look
The documents are few and known in advance: a salary certificate, and others only in particular cases. After them, a summary shows the whole loan on one screen, amount, installment, term, insurance, grace period, to confirm or go back and change. Submitting it creates the draft application.
TODO (Guillem): the upload, summary and "request submitted" screens.
A process with people in it
What happens next is not instant, and the design does not pretend it is. A new team at the bank, the digital lending team, checks each application, as the relationship officer did at the branch. A document can be unreadable; a salary may not match its certificate. The application then goes to underwriting, and from there to the final contract and funding.
The tracker turns that into numbered steps in the customer’s language: we’re reviewing your application, approve your draft contract, we’re finalizing your loan, sign your final contract, your funds are coming. The same place is where the bank can ask for something: a clearer document, a signature.

 We’re reviewing your application
 Approve your draft contract
 We’re finalizing your loan
 Sign your final contract
 Your funds are coming
 Loan details

 Check my digital signature
Your 0% loan
REF: 64546435
 Your application must be verified and completed within 2 business weeks.
1. We’re reviewing your application. The application has been sent and the bank is reviewing it. Loan details and the digital signature check are one tap away.
TODO (Guillem): one example of the bank asking for a document again.
Signing without a branch
The hardest question was not on any screen. The legal position had always been a signature on paper. The alternative was the digital signature of Kuwait’s mobile ID, which few people had, few knew existed, and which expired after a year.
TODO (Guillem): how this was resolved, and what the flow does for a customer whose digital signature is not ready.
After the money arrives
A funded loan gets a screen of its own: what is left to pay out of the total, the next installment and its date, the repayment schedule and the documents. From it a customer can pay part of the loan or all of it early, and see the new balance at once.
The loan announces itself. The day the money lands, a notification says so; it opens on one screen that says it again, loudly, and one button from there is the loan.

9:16
Monday, November 15


swipe up to open
TODO (Guillem): a partial payment and its confirmation; whether skipping an installment was designed.
Outcome
TODO (Guillem): what shipped and when, or how far it got; what testing said; any number of its own.